

Demo Example
Demo Example
Demo Example
Tag

actual cash value

Browsing

A car is declared a total loss when it cannot be repaired, or when repairing it costs about as much as the car is worth. The Texas Department of Insurance puts the test plainly: "If the cost to repair the car is about the same or more than the value of your car, the insurance company will likely consider it totaled." The Washington State Office of the Insurance Commissioner describes the same situation and states what follows from it: "The insurer owes you the actual cash value of your totaled car." The comparison that decides it is repair cost against the car's own value, not against what you paid or what you owe.

This article explains how a determination is made and how it is documented. It is educational information, not financial, insurance or legal advice. For a question about your own vehicle or claim, speak to a licensed agent, your insurer or your state Department of Insurance.

Sources checked August 10, 2026. Total loss rules, valuation requirements and title branding are set state by state, in statute and in administrative rule, and they differ substantially. Only your own state's current rule applies to you.

It is three decisions, not one

The phrase "declared a total loss" sounds like a single moment. In practice it is three separate determinations, made in order, and each one is governed by a different part of a state's rules.

One: the test. Is the vehicle a total loss at all? This compares the cost of repair against the vehicle's value.

Two: the valuation. What is the vehicle worth, and what may be added to or subtracted from that figure?

Three: the title. Does the vehicle's title get branded, and what has to happen before it can be driven again?

Most explanations of this topic answer only the first and treat the other two as consequences. They are not consequences. They are separately regulated, and a vehicle can clear one threshold without clearing another. Keeping them apart is the fastest way to understand why two people in two states describe the same event completely differently.

The test, and why there is no national version of it

The comparison itself is simple. Repair cost on one side, the vehicle's own value on the other.

The Texas Department of Insurance describes it as the repair cost being "about the same or more than the value of your car." The Washington State Office of the Insurance Commissioner describes a total loss as a car that "isn't repairable after an accident or the repairs cost more than what it's worth."

What differs between states is how that comparison is defined in law. Some states write the test into statute or administrative rule with a specific standard; others leave the comparison to the insurer within general claim-handling rules. The result is that the same damaged vehicle can be handled differently depending on where it is titled and insured.

This article does not print a national threshold percentage, and you should be careful with any article that does. Figures of that kind are compiled from many state sources at a moment in time, they are not uniform, and they change when a legislature or a department amends a rule. The reliable version of this number for you is the one your own state publishes.

To find it: go to your state Department of Insurance's consumer pages and look for total loss or auto claim settlement guidance, then check your state's motor vehicle agency for the title side. The National Association of Insurance Commissioners maintains the directory of state departments.

The valuation, and what a state rule can actually control

This is where state rules get specific, and where an example is worth more than a generalization.

The Washington State Office of the Insurance Commissioner sets out how the value is built. The insurer may offer to replace the car with "a comparable car in your local area," or pay "the actual cash value of comparable cars in your local area," or use appraisal provisions if the policy contains them. If comparable vehicles are not found locally, the insurer can expand the search "25 miles at a time until it finds two or more comparable cars," and with the owner's permission may search beyond 150 miles. The insurer must also "add to the actual cash value any taxes, license fees and other fees required to transfer ownership." If the owner keeps the vehicle, "the insurer removes the value of salvaging it from what they owe you."

Illinois regulates the same process through 50 Illinois Administrative Code Part 919, and the detail there shows how far a state rule can reach. The company must replace the property, repair it, or pay the loss in cash. Retail value is determined using "guidebooks or computerized data marketed by various sources," and written dealer quotes may be used where a vehicle is not listed. "Advertisements are not acceptable sources of market value." Deductions have limits: betterment deductions for prior collision damage are uncapped, while deductions for wear and tear, missing parts and rust are capped at $500.00, and all deductions must be itemized with specified dollar amounts. Whether an owner may keep the vehicle is also restricted, with exceptions described for vehicles with only hail damage that does not affect safety and for vehicles "nine (9) model years of age or older." Within 30 days of a cash settlement, an owner who buys or leases another vehicle may claim sales tax and title fees.

Read that Illinois list again and notice what kind of document it is. These are not industry customs. They are administrative rules with dollar figures in them, published by a state, applying in that state only. The $500.00 cap above is Illinois's number. Nothing here suggests it applies anywhere else.

The valuation standard underneath all of this is actual cash value, which is the depreciated value of the vehicle at the time of the loss rather than the cost of a new one. What that standard means and how it differs from replacement cost is set out in actual cash value versus replacement cost.

The document to ask for, and why you have to ask

Here is the most useful sentence found in this research, and it is one that almost no article on this topic repeats.

The Washington State Office of the Insurance Commissioner tells consumers to request a total loss valuation report, which "shows the data they used to decide your car's value," and adds: "The insurer might not provide this report unless you ask for it."

That is a regulator stating that the underlying working is available and that it is not automatic. The report is where the comparable vehicles, the adjustments and the deductions become visible as numbers rather than as a single settlement figure.

Washington also notes the mechanism that exists when the two sides do not agree: "If you and your insurer can't agree on your car's value, you may have the right to hire an appraiser. Your auto insurance should allow this." That right, where it exists, lives in the policy itself, which is one more reason to be able to find your way around it. The method is in how to read an insurance declarations page.

The title, which is a separate system entirely

The insurance decision and the title decision are made by different institutions, and confusing them causes real problems later.

The Texas Department of Insurance describes the title side for Texas: a totaled vehicle "may be issued a salvage title," and after it is repaired, "you'll need to get a new title from the Texas Department of Motor Vehicles before you can drive it." The same page carries a plain warning: "a vehicle that had a salvage title could be harder to sell or insure in the future."

Two consequences worth holding onto.

The first is that a branded title is a permanent property of the vehicle rather than a temporary status. It follows the car.

The second is that the agency that brands titles is not the insurance department. Title rules sit with the motor vehicle agency, under a different set of statutes, with their own thresholds and their own procedures.

Which coverage is doing the paying

A total loss is an event; it is not a coverage. Whether anything is paid at all, and by whom, depends on what the policy carries and what caused the loss.

The physical damage coverages that respond to a totaled vehicle, and the difference between the one that covers impact and the one that covers everything else, are set out in liability, collision and comprehensive. The deductible comes off the payment, and how a deductible interacts with a limit is worked through in premium, deductible, limit, out-of-pocket.

And the payment is measured against the car, not against the loan. If a loan balance is above the vehicle's value, the settlement does not rise to meet it. That space is exactly what gap coverage addresses, and how it is structured is explained in gap insurance explained.

The honest limitation of this article: it can tell you what determinations are made and where the rules governing them are published. It cannot tell you what any specific vehicle is worth, whether a particular offer is correct, or what a state's threshold is, because those are facts about a car, a company and a jurisdiction that are not visible from here. Valuation disputes and title questions are matters for your state Department of Insurance, your state motor vehicle agency, and where a legal right is in question, an attorney.

What to do with a determination in front of you

  1. Ask for the total loss valuation report. Washington's regulator says it may not arrive unless requested.
  2. Read what was added. Transfer taxes and fees may be required additions in your state.
  3. Read what was subtracted, item by item. Illinois requires deductions to be itemized with specified amounts, and some states cap certain categories.
  4. Find your state's rule on your Department of Insurance's site rather than in a national summary.
  5. Check the policy for an appraisal provision, which is the mechanism for a disagreement about value.
  6. Ask about the title separately. It is a different agency and a different question.
  7. Check the loan balance separately again. It is a third document with no reference to the other two.

This site explains documents and contracts. It does not tell anyone whether an offer is fair, what a vehicle is worth, or what to do about a specific claim. How sources are chosen on this site is set out in our editorial policy.

Frequently asked questions

What is the actual test for totaling a car?
Repair cost compared against the vehicle's own value. The Texas Department of Insurance describes it as repair cost being "about the same or more than the value of your car." How that comparison is defined in law varies by state, so the authoritative version is your state's.

Is there a standard percentage at which a car is totaled?
Not a national one. The specific standard is set state by state, in statute or administrative rule, and this article does not print a representative figure because a figure from the wrong state is misleading. Your state Department of Insurance publishes the rule that applies to you.

What is a total loss valuation report and how do I get it?
It is the document showing the data used to value your car. The Washington State Office of the Insurance Commissioner advises requesting it and notes that "the insurer might not provide this report unless you ask for it."

Can I keep my car after it is totaled?
It depends on the state and the circumstances. Washington's regulator states that if you keep it, the insurer removes the salvage value from what it owes. Illinois restricts retention, with exceptions described for vehicles with only hail damage that does not affect safety and for vehicles nine model years of age or older.

Does a totaled car always get a salvage title?
Not automatically, and the rule sits with the motor vehicle agency rather than the insurance department. The Texas Department of Insurance states that a totaled vehicle "may be issued a salvage title" and that a new title from the Texas Department of Motor Vehicles is required after repair before it can be driven.


Sources: Texas Department of Insurance, "My car was totaled! Now what?", last updated July 23, 2026. Washington State Office of the Insurance Commissioner, "What happens after your car gets totaled" (no date shown on the page). Illinois Department of Insurance, "Total Loss Auto Claims with Your Insurance Company," describing 50 Illinois Administrative Code Part 919 (no date shown on the page). All accessed and checked August 10, 2026. Every threshold, cap and procedural rule above is attributed to the state that publishes it. No national total loss threshold is stated, because the rules are set state by state.
A renters policy is four coverages sold together, not one. Coverage C pays for your personal property. Coverage D, loss of use, pays additional living expenses if the place becomes uninhabitable. Coverage E is personal liability. Coverage F pays medical expenses for people injured at your place. The California Department of Insurance sets out all four, and North Carolina's department names the same structure.

This article explains how a renters policy is put together. It is educational information, not financial, insurance or legal advice. For a question about your own coverage, speak to a licensed agent or your state Department of Insurance.

Policy structures checked August 10, 2026. Forms, minimums and available options differ by state and by company. Your own policy document is the authority for your contract.

What the landlord's policy is actually for

Almost every renter has heard that the landlord has insurance. That is true, and it is also the source of the most expensive misunderstanding in this entire subject.

Three regulators say the same thing in almost the same words. The California Department of Insurance: "Your landlord does not provide insurance for your personal property." The North Carolina Department of Insurance: "Your landlord's insurance does not cover your personal property or provide liability protection in the event of a loss." The Texas Department of Insurance: "Your landlord's insurance won't cover your personal items."

Washington's Office of the Insurance Commissioner puts the division most simply. The landlord's policy "covers the structure but provides no coverage for your belongings."

So the landlord's policy is a policy on the building, bought by the person who owns the building, to protect the person who owns the building. It is not thin, and it is not stingy. It is simply a contract about a different asset. Everything you moved in with sits outside it, and so does your own liability.

Coverage C: your things, wherever they are

The first coverage is the one everybody expects, and it is broader than most renters assume in one specific way.

The North Carolina Department of Insurance describes Coverage C as protection "for the contents of your home and other personal belongings owned by others who live with you." The Texas Department of Insurance adds the part that surprises people: it covers your belongings "even items stolen out of your car or while you're traveling."

That is worth sitting with. The coverage attaches to the property rather than to the address. A laptop taken from a car in a parking garage, or a suitcase lost to theft on a trip, is generally the same coverage responding, subject to the policy's terms.

On the California Department of Insurance's table, Coverage C is "an amount, designated by the insured, subject to a minimum as determined by your insurance company." So the number is a choice you make at purchase, within a floor the company sets. It is the only one of the four coverages where you pick the figure directly, and as the next section shows, it quietly decides a second number too.

Coverage D: loss of use, and where its number comes from

This is the coverage that pays when the apartment is not livable, and its limit is not something you are usually asked about.

The California Department of Insurance's renters table gives it in one line: "Coverage D – Loss of Use – 20% of Coverage C." The North Carolina Department of Insurance states the same relationship: "Coverage D is normally limited to 20% of Coverage C."

The consequence is the part nobody mentions at the point of sale. Loss of use is calculated from your contents limit. A renter who chooses a low contents number to keep the premium down has, in the same decision, chosen a low ceiling on the money that pays for somewhere to sleep after a fire. Those two things feel unrelated and they are mechanically linked.

What the coverage actually pays for is the difference between normal living costs and increased ones, not the whole cost of living elsewhere. The North Carolina Department of Insurance describes it as helping "with additional living expenses if your home is damaged by a peril insured against to the extent that you cannot live in your home," and notes the company reimburses amounts above normal living costs. The mechanics of that calculation are worked through in loss of use and additional living expense.

Coverage E: personal liability

The third coverage has nothing to do with your possessions and is the reason many leases require a policy at all.

Personal liability responds when you are found legally responsible for injuring someone or damaging their property. Washington's Office of the Insurance Commissioner frames it as protection if you are "found legally responsible for injuring someone or damaging their property." The California Department of Insurance shows Coverage E as "generally subject to a minimum of $100,000."

Two features distinguish it from the property coverages. It generally follows you rather than staying at the apartment, and it typically includes the cost of defending a claim as well as paying one, which is often the larger number.

A note on the shape of this article's subject: liability is where a renters policy and a homeowners policy look most alike. The lettering is the same because the underlying policy family is the same, which is why the six coverage parts A through F reads across to a renters policy for E and F even though A and B do not apply to a tenant.

Coverage F: medical payments to others

The fourth coverage is small, specific, and almost nobody who buys a renters policy knows it is there.

The North Carolina Department of Insurance defines it precisely: "This coverage pays for reasonable and necessary medical expenses for persons, other than resident members of your home, who are accidentally injured on your property." Washington's Office of the Insurance Commissioner describes it as paying the medical costs "of others accidentally injured at the place you rent." The California Department of Insurance shows Coverage F as "generally subject to a minimum of $1,000."

The important structural point is the difference between Coverage E and Coverage F. Liability turns on legal responsibility. Medical payments does not. It is a small sum, available for an injury to a guest, without anyone establishing that you were at fault. It exists partly to settle small incidents before they become liability claims.

Note the exclusion built into the definition: it covers people other than resident members of your household. It is not health coverage for you or the people you live with.

Actual cash value is the default, not the exception

Of everything in a renters policy, this is the term most likely to disappoint at the worst possible moment, and it is chosen at purchase.

Washington's Office of the Insurance Commissioner states that renter insurance typically covers belongings at "actual cash value at the time it was damaged, destroyed, or stolen" rather than replacement cost.

The Texas Department of Insurance publishes an example that makes the abstraction concrete: "Let's say you paid $1,300 for a laptop two years ago, but now the same kind is selling for $500. A basic renters policy would pay $500 if your laptop was destroyed." The department adds that replacement cost coverage exists: "You can buy a policy that will cover the replacement value of your items, but it will cost more."

So the default settlement basis is depreciated value, and the alternative is an option you have to ask for. This is the same distinction that runs through the whole property side of insurance and it is set out in full in actual cash value versus replacement cost.

There is a second limit stacked on top of the valuation question. Certain categories of property are capped separately inside the contents limit. The Texas Department of Insurance gives examples: "Common limits are $100 for cash, $2,500 for items used for business, and $500 for jewelry and watches." Washington's office notes that a scheduled personal property endorsement is how those caps are raised. What those caps are and how they behave is covered in sub-limits on jewelry, cash and electronics.

What a renters policy does not cover

A renters policy is a named-peril contract, which is a structural fact rather than a list of unlucky exceptions.

The North Carolina Department of Insurance describes the policy as covering 14 specific perils, including fire, windstorm, theft, vandalism and water damage from plumbing systems. If the cause of loss is not on the list, the policy does not respond. Why that matters, and how it differs from an open-perils contract, is explained in named perils versus open perils.

Washington's Office of the Insurance Commissioner names the main gaps directly. A renter policy does not cover structural damage to the building itself. It does not cover earthquakes, floods, landslides or sinkholes. It does not cover a home business without specialized coverage, and it does not cover theft of or damage to a vehicle, which is auto insurance territory. The Texas Department of Insurance makes the same point about flooding: renters policies "don't cover losses due to floods."

Two of those gaps have their own separate contracts, covered in why flood is a separate policy and earthquake insurance as a separate policy.

What to check before you sign

  1. Read what the contents limit is, and then work out 20 percent of it, because on the standard structure that is your loss of use ceiling.
  2. Ask whether the policy settles at actual cash value or replacement cost, and get the answer in writing on the declarations page rather than in conversation.
  3. Ask for the special limits list and check it against what you actually own, particularly jewelry, cash and anything used for work.
  4. Confirm the liability limit and ask whether defense costs sit inside or outside it.
  5. Ask which perils the form names, and confirm flood and earthquake are outside it, so nothing about that is a surprise later.
  6. Make an inventory before you need one. How and why is covered in building a home inventory.

Your state Department of Insurance publishes the consumer material this article draws on and handles complaints about how a company administers a policy. The National Association of Insurance Commissioners maintains the directory of state departments. A licensed agent in your state can tell you which forms and options are available where you live.

This site explains documents and contracts. It does not tell anyone how much coverage to buy or which company to buy it from, because that depends on what you own, where you live and your own circumstances, and none of those is visible from here. How sources are chosen on this site is set out in our editorial policy.

Frequently asked questions

Does my roommate's renters policy cover my things?
The North Carolina Department of Insurance describes Coverage C as protecting "the contents of your home and other personal belongings owned by others who live with you," which is a description of how one policy's contents coverage is worded rather than a rule about roommates generally. Whether a specific policy covers a specific person is a question for the agent who wrote it, and it should be asked before a loss rather than after.

Is renters insurance required by law?
The regulator material reviewed here does not describe it as a legal requirement. It is commonly required by a lease, which is a contract between you and a landlord rather than a state rule. Your lease is the document that answers this.

Does renters insurance cover my car?
No. Washington's Office of the Insurance Commissioner lists theft of or damage to a vehicle among what a renter policy does not cover, and points to auto insurance instead. Property inside the car is a different question and is generally handled under the contents coverage, subject to the policy's terms.

What is the difference between Coverage E and Coverage F?
Coverage E responds when you are legally responsible for injury or damage. Coverage F pays reasonable and necessary medical expenses for a person other than a resident of your household who is accidentally injured on your property, and it does not require a finding of fault. They are separate coverages with separate limits.


Sources: California Department of Insurance, "Residential Insurance: Homeowners and Renters," Form 401, revised January 2026. North Carolina Department of Insurance, "Renters" (no date shown on the page). Texas Department of Insurance, "Renters insurance: What does it cover and how much does it cost?", last updated December 10, 2025. Washington State Office of the Insurance Commissioner, "How renter insurance works" (no date shown on the page). All accessed and checked August 10, 2026. The Virginia SCC renters guide, the Florida Department of Financial Services renters page and the New Jersey renters publication could not be retrieved during this research and nothing is sourced to them.

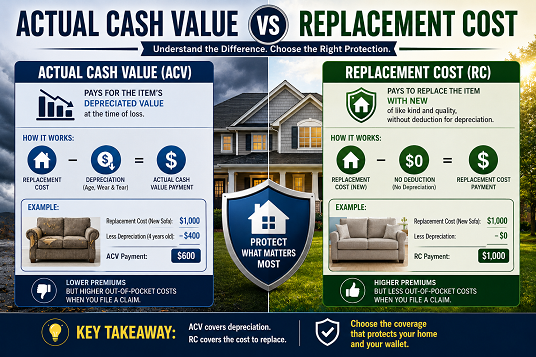
Actual cash value pays based on what the property is worth now, after age and wear are taken into account. Replacement cost pays what it costs to repair or replace with materials of like kind and quality, without that reduction. The NAIC states that actual cash value coverage "often does not pay enough to fully replace your property or repair the damage." The difference between them is depreciation, and which one applies is recorded on your own policy.

This article explains two policy terms. It is educational information, not financial, insurance or legal advice. For a question about your own coverage, speak to a licensed agent or your state Department of Insurance.

Of everything printed on a homeowners or renters declarations page, this is the item with the largest consequence and the smallest font. It is usually a single word or an abbreviation sitting beside a coverage, and it decides how every payout under that coverage is calculated. If you have not located it yet, how to read an insurance declarations page shows where the valuation line normally sits.

The two definitions, as the regulators state them

Two regulators state the distinction plainly, in slightly different words, and having both is more useful than having either.

The NAIC, in a consumer article dated January 2, 2025, puts it this way. Under actual cash value coverage, the policy "will pay the cost to repair or replace your home or personal property based on its value, considering its age and wear and tear (depreciation)," and the NAIC adds directly that this "often does not pay enough to fully replace your property or repair the damage." Under replacement cost value coverage, the policy "will pay the cost to repair or replace your damaged property using materials of a like kind and quality."

The North Carolina Department of Insurance restates the same split in more concrete terms. Actual cash value is "the amount of money needed to fix your home, minus the decrease in value of your property because of age or use." Replacement cost value is "the amount of money needed to repair your home at today's prices of building supplies; or replace your belongings at today's cost of the similar or like item."

Actual cash value Replacement cost value
Basis of payment Current depreciated value Cost to repair or replace with like kind and quality
Age and wear Subtracted Not subtracted
Regulator's caution NAIC: "often does not pay enough to fully replace your property" None stated
Typical effect on premium Generally the lower-premium option Generally the higher-premium option
Where it is recorded Your declarations page and the endorsements it lists Your declarations page and the endorsements it lists

Depreciation is the entire difference

Strip away the terminology and there is one variable. Both bases start from the same question, which is what it would take to repair or replace the property. Actual cash value then subtracts an amount for age and use. Replacement cost does not.

The Iowa Insurance Division, in a consumer guide published on April 4, 2024, defines the two in exactly that relationship, describing actual cash value as "replacement cost less depreciation" and replacement cost as reimbursing you to purchase a new item at current market value.

The size of that subtraction depends on the property. A roof covering, a water heater, a laptop and a sofa all lose value with age on different schedules, and a ten-year-old item under an actual cash value policy is valued as a ten-year-old item. That is not a defect in the coverage. It is what the coverage says it will do, which is why the word on the page matters more than any assumption about fairness.

How any withheld depreciation is treated afterward is governed by the policy language and by state rules. That is a settlement question rather than a policy-reading question, and the place to establish it is your own policy form and your state Department of Insurance.

Where these words appear on your own policy

The regulators define the terms. Notably, the NAIC's article does not go on to explain how a policyholder identifies which one applies to their own policy, so that part is worth setting out.

There are three places to look, in order.

The declarations page, beside the coverage. On a homeowners policy the valuation basis usually appears next to Coverage A dwelling and next to Coverage C personal property. It may be spelled out, or abbreviated as RC, RCV or ACV, or expressed as a coverage option code.

The form and endorsement list on the same page. Replacement cost on personal property is often added by an endorsement rather than being part of the base form. If it is there, it appears in that list as a form number, and that number is what you ask your insurer for if you want the exact wording.

The base policy form. The definitions of both terms, and any schedule of property they are applied differently to, live in the form itself rather than on the summary page.

If the words appear nowhere you can find, that is a question for your insurer, and the phrasing that gets a precise answer is "on what valuation basis is Coverage A settled, and on what basis is Coverage C."

A single policy can use both

This is the part most explanations skip. The valuation basis is not one setting for the whole policy. It is set per coverage.

The Iowa Insurance Division makes this explicit for personal property, stating that Coverage C "may be actual cash value (replacement cost less depreciation) or replacement cost." That is a separate determination from the one made for the structure.

The common combination is replacement cost on the dwelling and actual cash value on contents, because contents are where depreciation bites hardest and where the premium difference shows up most. A household can therefore be reading its declarations page correctly, see "replacement cost" next to Coverage A, and still hold actual cash value coverage on everything inside the house.

Some policies also carve out specific categories for different treatment. Roof coverings and certain classes of personal property are the usual examples, and where that is done it is done by endorsement, which means it appears in the form list on your declarations page.

The practical instruction is to read the valuation basis for every coverage separately rather than reading it once.

"Like kind and quality," and what it does not promise

The NAIC's replacement cost definition turns on the phrase "materials of a like kind and quality." It is worth being precise about what that phrase does and does not do.

It sets a comparability standard, not an upgrade. Replacement cost means replacing what was there with something equivalent at today's prices. It does not mean an improvement on what was there, and it does not mean that the exact discontinued item will be found.

It also does not remove the limit. Replacement cost governs how a loss is valued. The coverage limit still governs the maximum payable, and the deductible is still subtracted. A replacement cost policy with a dwelling limit below what rebuilding would actually cost pays up to that limit, and no valuation word changes that. The relationship between limits and deductibles is covered separately in premium, deductible, limit, out-of-pocket.

Four neighboring terms that are not the same thing

Four other phrases appear in the same conversation and none of them is a synonym for either of the two. Worth flagging honestly: unlike actual cash value and replacement cost, these are not defined by a regulator in the sources reviewed here. Carriers define them, and the wording varies, so the only reliable definition is the one in your own policy.

Extended replacement cost. Replacement cost with an additional cushion above the dwelling limit, expressed as a stated percentage. The percentage is a policy term, printed on your own declarations page or endorsement, and there is no standard figure to quote.

Guaranteed replacement cost. Marketed as paying the cost to rebuild without the dwelling limit acting as a cap. Availability and conditions vary by carrier and by state, and the conditions are in the endorsement.

Functional replacement cost. Replacement using contemporary materials that serve the same function rather than matching obsolete construction. It is common on older homes.

Market value. What the property would sell for, which includes land and location. It is not a valuation basis for insurance at all, and it can be far above or far below the cost to rebuild. Confusing rebuild cost with market value is one of the more common misunderstandings in this area.

If any of these four appear on your paperwork, the endorsement number beside it is the document that defines it for you.

What neither term decides

The valuation basis answers one question only: how a covered loss is valued. It does not answer any of the following, and each of them is decided elsewhere in the contract.

  • Whether the loss is covered. That is the insuring agreement and the exclusions in the policy form.
  • How much can be paid. That is the limit for the applicable coverage.
  • What is subtracted first. That is the deductible, and on a homeowners policy there may be more than one. See flat vs percentage deductibles.
  • Whether a category is capped separately. Sub-limits on jewelry, cash and similar categories operate independently of valuation.
  • What your duties are after a loss. Those are the policy conditions.

A reader who knows their valuation basis and nothing else knows one useful thing. A reader who knows the basis, the limit and the deductible for each coverage can read their whole declarations page.

How to establish which basis your policy uses

  1. Read the valuation word next to each coverage separately, at minimum for the dwelling and for personal property.
  2. Check the form and endorsement list for a replacement cost endorsement, and note its number.
  3. Ask your insurer or agent for the base form and any valuation endorsement by number if you want the exact contract wording rather than a summary.
  4. Compare against last year's declarations page. A valuation basis can change at renewal.

For questions beyond reading the page, a licensed insurance agent can explain what your endorsement does and what changing it would mean for your premium. Your insurer's service line can confirm what is on file. Your state Department of Insurance is the neutral party, publishes consumer material on exactly this distinction, and handles complaints about how a company administers a policy. The National Association of Insurance Commissioners maintains a directory of state insurance departments.

This site explains documents. It does not tell anyone which valuation basis to carry, and that question genuinely depends on facts about a household that no article can see. How sources are chosen here is set out in our editorial policy.

Frequently asked questions

Which one does a standard homeowners policy use?
There is no single answer, because it is set per coverage and it varies by policy and by carrier. The Iowa Insurance Division notes that personal property may be written on either basis. The only reliable source for your own policy is your declarations page and the endorsements listed on it.

Is replacement cost always the better coverage?
The NAIC states that actual cash value coverage often does not pay enough to fully replace property or repair damage, and replacement cost generally carries a higher premium in exchange. Which trade-off suits a given household depends on facts about that household, and a licensed agent looking at the actual policy is the right person to weigh it.

Does replacement cost mean I get a brand new item for an old one?
It means repair or replacement with materials of like kind and quality, in the NAIC's words, valued at today's cost. It is a comparability standard rather than an upgrade, and the coverage limit and deductible still apply.

Is replacement cost the same as market value?
No. Market value is what a property would sell for and includes land and location. Replacement cost is what it would take to repair or rebuild. The two can differ substantially in either direction, and market value is not a valuation basis for insurance payouts.


Sources: National Association of Insurance Commissioners, "What's the Difference Between Actual Cash Value Coverage and Replacement Cost Coverage?", January 2, 2025. North Carolina Department of Insurance, "Actual Cash Value vs. Replacement Cost Value" (no date shown on the page). Iowa Insurance Division, "Consumer Connection: Understanding your Homeowners Policy," published April 4, 2024. All accessed August 5, 2026.